
Why the old way feels clunky
People here know how slow banks can be lah — queues, reams of paperwork, long underwriting timelines. After the COVID-19 pandemic sped up digital habits, many more customers wanted fast access to credit without the stress. That’s where solutions like didi prestamos come in, offering a streamlined take on revolving credit and digital onboarding. Fintech firms trimmed steps, added automation, and made approval faster, so users stop waiting lor and get funds when need pops up.
How DiDi Finanzas compares — practical differences
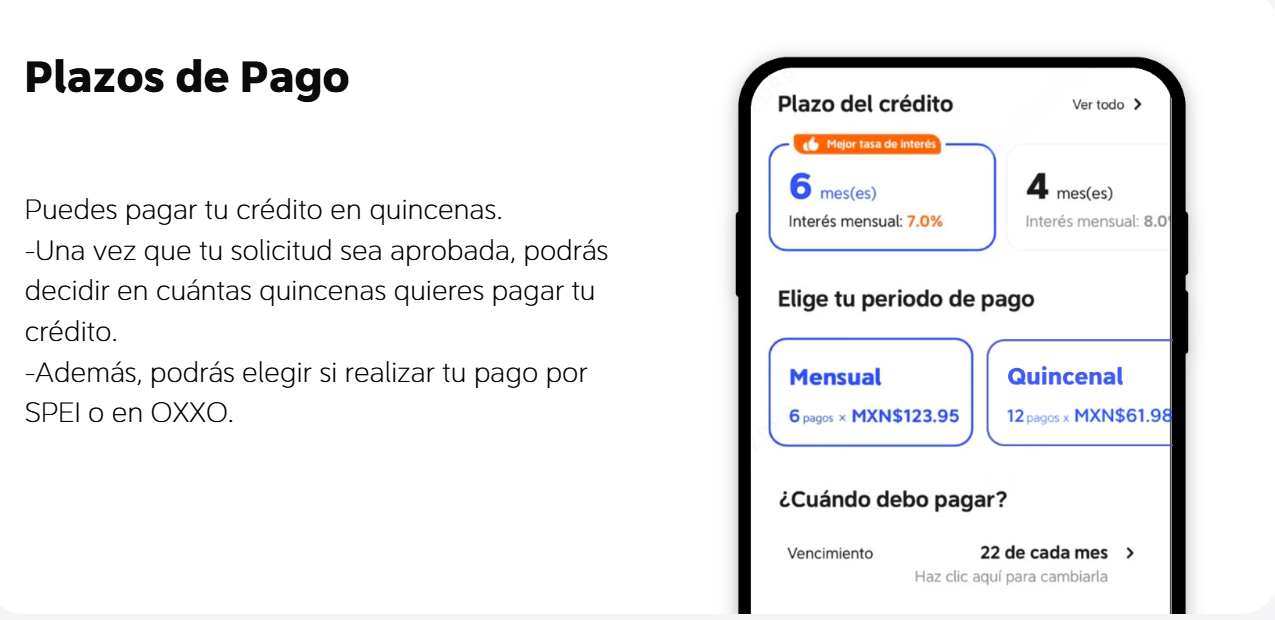
DiDi Finanzas designs the product around convenience. Compared with traditional banks: faster decisioning, mobile-first UX, and simpler eligibility checks. For many users the comparison comes down to three concrete items: speed of disbursement, clarity of APR, and account controls. The platform focuses on clear APR presentation and ongoing account management so the borrower knows how the revolving credit line will behave month to month.
Feature breakdown — what actually changes for you
Look, functionality not just pretty UI. DiDi Finanzas builds APIs that connect to identity checks and payment rails, which cuts manual verification time. That means less back-and-forth and fewer surprise holds. For everyday borrowers the wins are tangible: quick digital onboarding, predictable repayment schedules, and in-app notifications that stop bills from sneaking up. Underwriting still matters — automated models speed it up but they still need reliable data inputs.
Practical comparison with alternatives
Alternatives include credit unions, neo-banks, and other fintech lenders. Each has trade-offs:
– Credit unions: often lower rates but slower processes and limited digital tooling.
– Neo-banks: slick apps, sometimes limited credit products or shorter credit histories accepted.
– Other fintechs: fast but variable underwriting quality; check transparency on fees and repayment flexibility.
DiDi Finanzas sits in the middle — faster than a credit union, more product depth than some neo-banks, and designed for clear customer control. The platform also positions itself for prestamos en linea al instante for users who need short-term access without heavy negotiation.
Common mistakes people make
Borrowers often treat digital credit like free money. That habit kills budgets later. Another mistake: ignoring the effective APR and just looking at the monthly payment. Also, some users disable alerts — then cannot react when they near the credit limit. Fix these by checking APR, setting low autopay thresholds, and using notifications for balance changes — simple steps but steady impact.
Real-world anchor and credibility
Since 2020, the global shift to digital payments and remote services made consumers expect immediacy; regulators and banks reacted, too. That event pushed many lenders to adopt KYC automation and better fraud controls, so today’s digital lenders operate inside clearer safety rules. This context matters because any reliable fintech product must balance speed with compliance, otherwise risk and customer trust evaporate quickly.
Three golden rules to pick the right revolving credit
When evaluating providers, use these metrics: 1) Effective cost — compare APR and all fees over a typical year; 2) Operational speed — measure real approval-to-disbursement time, not marketing claims; 3) Control features — look for clear limits, notifications, and easy repayment options. Use these to judge user fit and financial impact.
Conclusion
DiDi Finanzas matches those rules with transparent APRs, rapid digital onboarding, and consistent account controls — a pragmatic choice if you want steady and predictable revolving credit for everyday needs. Final thought: make the product work for your cashflow, not the other way around.